
By Usman Aliyu, News Agency of Nigeria (NAN)
Africa’s drive in direction of a digitally related economic system is gaining momentum, with prompt cost methods providing the promise of sooner transactions, broader market entry and extra seamless cross-border commerce.
Yet fragmented cost networks, unequal entry to monetary providers, excessive transaction prices and rising fraud dangers proceed to forestall hundreds of thousands of individuals from totally benefiting from these advances.
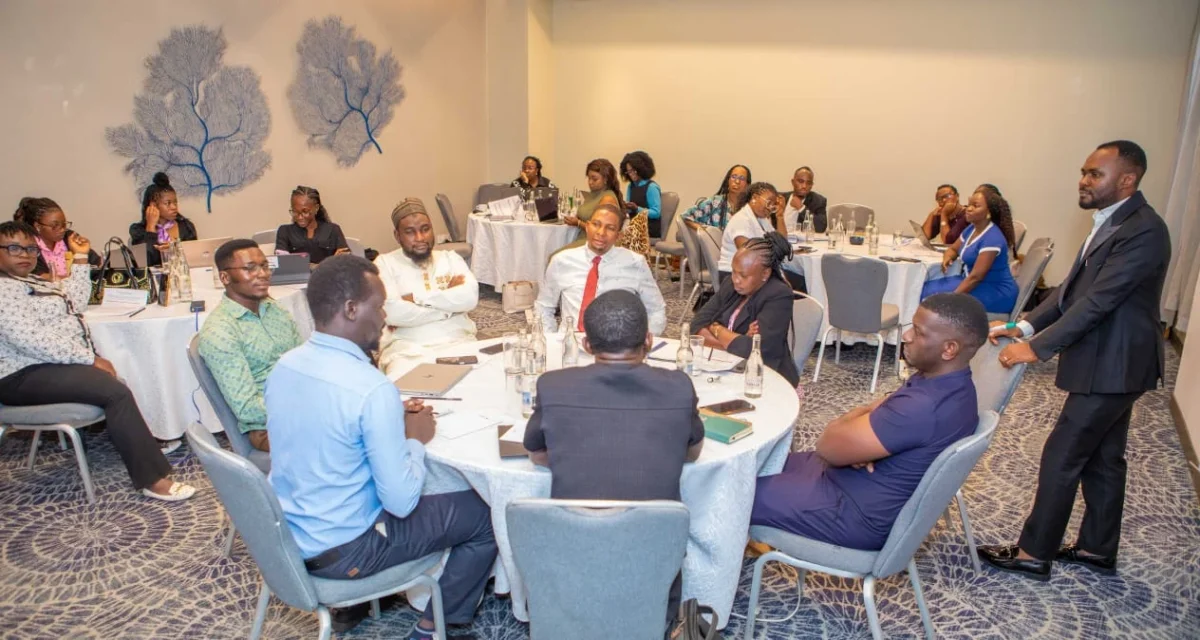
These challenges had been on the centre of discussions at a three-day workshop lately organised by the AfricaNenda Foundation in Nairobi, Kenya.
AfricaNenda Foundation is an African nonprofit organisation that works to speed up inclusive prompt cost methods so that folks throughout Africa, together with underserved communities, can entry and use digital monetary providers.
Its work focuses on making digital funds extra accessible, reasonably priced and interoperable, serving to people and small companies take part within the digital economic system.
The workshop introduced collectively 18 journalists and three communications officers from the African Union Commission to strengthen reporting on inclusive prompt cost methods (IPS) and monetary inclusion.
The discussions examined whether or not cost methods are mature, accessible, reasonably priced and dependable for atypical individuals, small companies and underserved communities, shifting the main target past expertise and transaction volumes to the experiences of those that use them.
During a session on monetary inclusion, Sabine Mensah, Deputy Chief Executive Officer of the AfricaNenda Foundation, posed a thought-provoking query: “Can consumers access the right information and conduct transactions easily, simply, affordably, anytime, anywhere, and instantly?”
Data offered on the workshop confirmed that about 75 per cent of African adults personal cellphones, whereas 58 per cent have a financial institution or cellular cash account.
However, about half of the continent’s grownup inhabitants based on the cited information, makes use of cellular funds, leaving roughly 49 per cent exterior their use.
The figures clearly spotlight the hole between entry to cellular expertise and significant participation in digital finance.
John Muthiora, Technical Payment Specialist on the AfricaNenda Foundation, defined that inclusive prompt cost methods should join totally different classes of licensed monetary establishments reasonably than function in remoted networks.
He famous that bilateral preparations between banks, cellular cash operators and different suppliers required separate agreements, connections and settlement preparations, growing prices and operational calls for.
A multilateral system, against this, he stated, allowed a collaborating establishment to attach as soon as and transact throughout a wider monetary ecosystem.
“Multilateral in this sense means one gives you access to many,” Muthiora stated, explaining that such infrastructure might join banks, cellular cash operators, fintechs and microfinance establishments.
According to Muthiora, the target, is to scale back the complexity and price of transferring cash between suppliers, making transactions cheaper and simpler for customers.
Multilateral, he stated, was the very best in constructing an inclusive prompt cost system.
However, connectivity alone doesn’t assure inclusion. Muthiora stated methods should additionally accommodate individuals utilizing fundamental cellphones, notably in rural communities the place smartphones, electrical energy and dependable web entry is perhaps restricted.
He harassed that an inclusive system ought to serve individuals whose entry to monetary providers relied on fundamental telephones, microfinance establishments or community-based monetary organisations.
Nigeria’s lead—and the gaps that stay
The workshop additionally examined AfricaNenda basis’s framework for assessing prompt cost methods, which labeled them into three ranges: fundamental, progressed and mature.
Serge Ambadiang, Partnership, Advocacy and Capacity Building Specialist on the basis, stated the evaluation lined 36 home and regional prompt cost methods in Africa.
The figures offered on the workshop positioned 15 methods on the fundamental stage and 10 on the progressed stage, whereas 10 had not been rated. Nigeria’s NIBSS Instant Payment (NIP) system was recognized because the continent’s solely mature-level system underneath the framework.
NIBSS stands for Nigeria Inter-Bank Settlement System. It is a Nigerian monetary expertise and cost infrastructure firm that facilitates digital funds and transactions between banks and different monetary establishments in Nigeria.
NIBSS performs an vital position in Nigeria’s digital monetary ecosystem by means of providers resembling:
NIBSS Instant Payments (NIP). This allows prompt digital transfers between financial institution accounts and collaborating monetary establishments.
Ambadiang defined that basic-level methods usually help person-to-person and service provider funds however lack the broader interoperability and governance preparations wanted for additional improvement. He, nevertheless, famous that progressing in direction of maturity required greater than including transaction choices.
“Systems must support a wider range of use cases, provide effective consumer complaint and redress mechanisms, and maintain sustainable cost-recovery models that keep services affordable.”
Cross-border funds and the price of fragmentation
Participants on the workshop agreed that Cross-border funds remained a significant problem. And that Businesses and people continued to face obstacles when transferring cash throughout jurisdictions with totally different currencies, rules and cost infrastructures, regardless of regional efforts to enhance connectivity.
A examine mentioned throughout the workshop estimated that about $5 billion may very well be misplaced yearly by means of foreign money conversion routed through the US greenback or different currencies in cross-border funds.
The examine additionally estimated that about $1 billion a yr might return to households in charges on 100 million transfers if fees had been lowered to a 3 per cent goal.
These estimates underline the potential advantages of lowering the price of cross-border transactions. For small and medium-sized enterprises, smoother funds might widen markets and cut back the fee and inconvenience of buying and selling with clients and suppliers in different African nations.
Harmonising Africa’s cost panorama
Addressing the regulatory obstacles, Dr Patrick Olomo, Head of Economic Policy and Sustainable Development on the African Union Commission, stated the AU and AfricaNenda had been working since 2023 in direction of regulatory harmonisation to facilitate seamless digital funds throughout African nations.
The initiative, he defined, was not about creating one other cost infrastructure, however making present methods successfully and effectively work collectively.
“One of the fundamental challenges that we have is that there is so much fragmentation and so much friction on the regulatory side of things,” Olomo stated.
With 55 African Union member states and about 40 central banks, he stated, frequent guidelines and regulatory understanding had been important to bettering cross-border funds and advancing monetary inclusion.
There was a way of reduction when Jacqueline Jumah, AfricaNenda’s Director of Advocacy and Capacity Development, stated a feasibility examine had discovered {that a} harmonised regulatory framework was legally, technically, institutionally and economically achievable.
She famous, nevertheless, that implementation would require binding continental guidelines, interoperable methods, acceptable governance and a phased roadmap that recognised variations in nations’ ranges of digital improvement.
She recognized eight precedence areas: licensing and passporting; interoperability requirements; anti-money laundering and buyer due diligence; client safety; information governance; supervisory cooperation; settlement and liquidity; and a binding African Union instrument.
“Without an enforceable continental basis, the other seven can remain voluntary and uneven,” Jumah stated.
Protecting customers and constructing belief
Beyond interoperability and regulation, members examined the dangers related to prompt funds, notably fraud and the issue of recovering cash as soon as a transaction has been accomplished.
Interoperability is the flexibility of various methods, establishments or applied sciences to attach and work collectively seamlessly, permitting them to trade info or perform transactions with out pointless obstacles.
In digital finance, interoperability implies that clients can ship and obtain cash between totally different banks, cellular cash operators and different monetary service suppliers, even once they use totally different platforms.
Example: A buyer utilizing a cellular cash service in Kenya can switch cash to somebody with a checking account in Nigeria, supplied the related cost methods are related and help the transaction.
On this, Mensah, nevertheless, warned that “fraudsters exploit the same speed that makes instant payments convenient.”
She highlighted various kinds of cost scams within the evolving digital cost ecosystem.
In authorised cost scams, she stated victims had been manipulated into approving transfers, whereas unauthorised fraud concerned criminals accessing credentials or accounts and initiating transactions with out the account holder’s data.
Because funds might attain recipients inside seconds, she stated, recovering cash may very well be tough, notably “when it is withdrawn immediately.”
Mensah highlighted doable responses, together with recipient verification earlier than transfers, real-time fraud monitoring, stronger information-sharing amongst suppliers and clearer reimbursement preparations for victims.
She additionally harassed the significance of client schooling, noting that scams more and more exploited impersonation, social engineering and synthetic intelligence to deceive customers.
Sharing an analogous sentiment, Ambadiang stated client recourse was one of many difficult standards in figuring out whether or not a cost system had achieved maturity.
Consumers, he stated, wanted to know the place to complain, how rapidly instances can be resolved and what occurred when suppliers failed to deal with their grievances.
Without efficient redress, he stated, a system would possibly course of transactions immediately however battle to earn and retain public belief.
Journalism past official bulletins
For Jude Fuhnwi, AfricaNenda Foundation’s Media Lead, the workshop was designed to deal with gaps in journalists’ understanding of prompt cost methods and enhance the standard of public reporting.
He urged journalists to maneuver past official bulletins and examine whether or not methods labored for individuals exterior main city centres, the place community issues, affordability and restricted entry might undermine their advantages.
“As journalists, you have a wider audience,” Fuhnwi stated, noting that the media might carry customers’ experiences into coverage discussions typically dominated by regulators and technical consultants.
He stated members would turn into a part of AfricaNenda’s media coalition advancing inclusive prompt funds, which he described as a community for studying and impartial story improvement reasonably than a public relations platform.
Fuhnwi urged journalists to not rely solely on AfricaNenda’s reviews but additionally to interpret information from industrial banks and different sources and look at how cost methods carried out in apply.
Similarly, Mensah urged journalists to amplify the experiences of customers who had been typically excluded from coverage discussions.
“We can leverage the media as an anchor to amplify what’s happening in the digital finance ecosystem,” Mensah stated.
Ultimately, Africa’s digital cost ambitions will rely not solely on how rapidly cash strikes, but additionally on who can entry these providers, how a lot they price and whether or not customers are adequately protected when issues go fallacious.
As African nations deepen regional commerce integration underneath the African Continental Free Trade Area, interoperable, reasonably priced and dependable cost methods shall be essential to enabling companies and customers to transact seamlessly throughout borders.
For policymakers and the journalists holding them to account, the duty is to make sure that the promise of prompt funds goes past velocity and comfort to ship tangible, inclusive and lasting advantages for the individuals and companies who want them most.(NANFeature)