
Daraju Industries Limited has opened a suggestion of as much as N10 billion Series 4 Commercial Paper beneath its N50 billion Commercial Paper Programme.
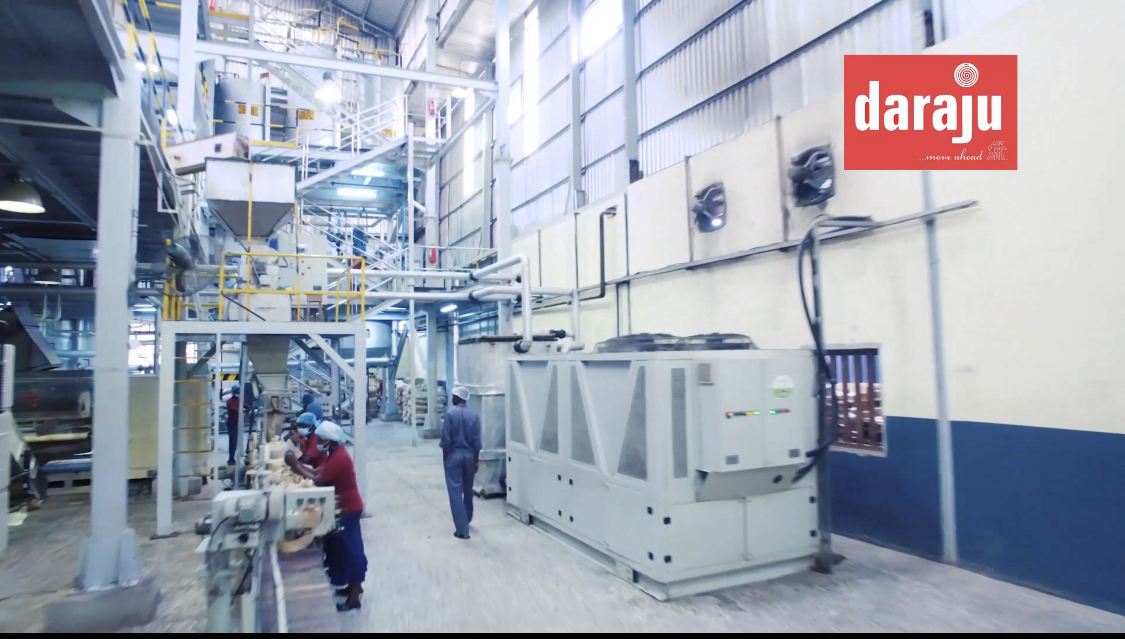
The Lagos-based producer, which started operations in 1988 and produces MYMY toothpaste, soaps and detergents, has been utilizing the market to boost cash for its short-term working capital wants
This supply carries an implied annual yield of 23%, that means buyers who maintain the paper till maturity would earn about 23% on the quantity invested, offered Daraju repays in full.
The supply opened on Thursday, October 8, 2026, and closes on Friday, October 16, 2026. The paper runs for 364 days.
What the supply round is saying
- Issuer: Daraju Industries Limited.
- Programme measurement: N50 billion.
- Series: 4 – goal measurement: Up to N10 billion.
- Tenor: 364 days.
- Discount fee: 18.7088% each year.
- Implied yield: 23% each year.
- Allotment date: Friday, October 16, 2026.
- Settlement/situation date: Monday, October 19, 2026.
- Maturity date: Monday, October 18, 2027.
- Minimum subscription: N5 million and multiples of N1,000 thereafter.
- Issuer rankings said in the supply: BBB- long run and A3 quick time period from GCR.
- Use of proceeds: To assist short-term funding wants.
The supply:
The issuance follows Daraju’s supply of as much as N5 billion Series 3 business paper in February 2026, which additionally carried a 364-day tenor and a 23% implied annual yield.
For the newest supply, proceeds will assist short-term funding wants. This supplies cash for the firm’s working capital for the day-to-day funding required to maintain its manufacturing and distribution enterprise operating.
For a producer akin to Daraju, these wants embrace shopping for uncooked supplies, producing items, and holding inventory earlier than buyer funds are acquired.
Investors earn income by buying the paper under its compensation worth and receiving that worth at maturity.
- For illustration, a paper with a compensation worth of N5 million would price roughly N4.067 million, utilizing the said low cost fee of 18.7088% and a 365-day calculation foundation.
- Receiving N5 million at maturity would produce roughly N933,000 in gross income, earlier than relevant taxes and charges.
The implied annual yield of 23% measures the income towards the quantity paid upfront.
Repayment is scheduled for October 18, 2027, following issuance on October 19, 2026. Investors obtain their cash at maturity, topic to Daraju assembly its obligation.
Investment case
Daraju’s 23% yield offers 4.17 share factors above the comparable Treasury invoice yield of 18.83%. This interprets to roughly N208,000 extra on N5 million truly invested over 364 days, earlier than taxes and charges, assuming full compensation.
Whether that sufficiently rewards buyers is determined by Daraju’s capacity to repay.
The firm has repeatedly issued CP, and its accounts file substantial combination debt repayments. However, these don’t set up that each matured CP collection was repaid on time.
- Daraju’s revenue leaves little room after borrowing prices. In 2025, working revenue of N15.65 billion was largely absorbed by finance prices of N13.26 billion, leaving simply N2.39 billion earlier than different income and tax.
- This means the firm earned about N1.18 for each N1 of financing prices, solely barely higher than N1.16 in 2024. Lower earnings or increased borrowing prices may rapidly take in that cushion.
- Operating revenue additionally included a N6.12 billion international trade achieve that didn’t carry money into the enterprise.
- Without it, working revenue would have been N9.53 billion—N3.73 billion wanting finance prices.
- Revenue elevated from N63.06 billion in 2023 to N110.82 billion in 2025 however fell 4.9% in first-half 2026. Nevertheless, half-year gross revenue elevated by 6.7%, indicating higher manufacturing margins. Coverage remained skinny at 1.21 occasions, or 0.91 occasions, excluding foreign money beneficial properties.
Renewed gross sales progress, higher manufacturing effectivity, and cheaper funding may enhance protection.
However, finance prices rose 53% in 2025, alongside a 21% enhance in borrowings and import finance. Further borrowing or increased enter prices may take in working enhancements.
The steadiness sheet stays stretched.
Borrowings of N60.22 billion had been 13.7 occasions fairness, down from 18.7 occasions as a result of fairness strengthened, though debt elevated.
- Current liabilities exceeded present property by N8.18 billion, making collections and entry to funding necessary.
- Cash era additionally faces competing calls for. Operating money of N7.11 billion fell under capital purchases of N7.40 billion, leaving adverse free money stream of N287 million earlier than individually disclosed curiosity funds.
- After these N4.24 billion funds, the deficit widened to N4.52 billion earlier than principal repayments.
The premium due to this fact warrants warning. Improving margins supply encouragement, however verified CP redemptions, funding for upcoming maturities and stronger money era would make the extra return extra persuasive.
Investor takeaways
The paper offers a 23% implied annual yield over 364 days, with income acquired by means of compensation at maturity.
Daraju’s established manufacturers and bettering manufacturing margins assist its enterprise, however borrowing prices go away restricted room for setbacks.
Investors ought to evaluate the extra income with Treasury payments of the same tenor, permitting for relevant taxes, charges and variations in liquidity.
Those needing their cash earlier than maturity ought to verify whether or not they can promote the paper and at what potential price.
Risk issues
However, the public sources reviewed didn’t present verified proof of delayed CP funds.
- Slower gross sales or buyer funds may enhance the want for contemporary borrowing to satisfy obligations.
- A weaker naira may increase imported-input prices and foreign-currency debt funds.
- Investors promoting earlier than maturity could battle to discover a purchaser at a beneficial worth.
The extra yield ought to due to this fact be weighed towards Daraju’s capacity to generate money and safe funding all through the funding interval.