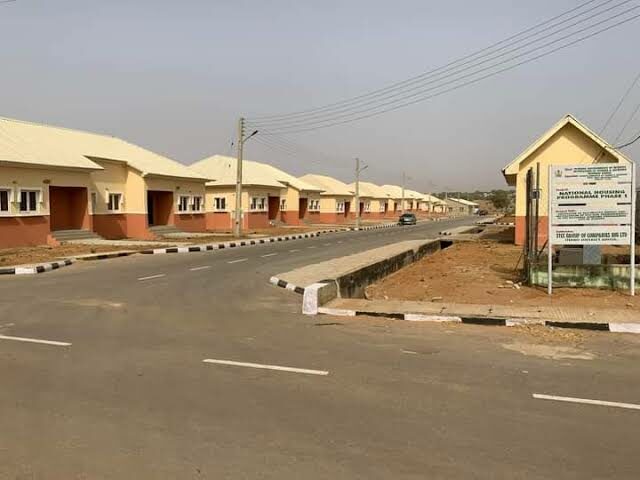
The Federal Government has introduced plans to ship 77,400 social housing items as a part of its renewed push to bridge Nigeria’s 28 million housing deficit, however the initiative is already elevating a vital query about affordability. While officers describe the challenge as focused at low-income earners, previous social housing schemes have usually ended up past the attain of the poor, priced out by excessive prices, mortgage necessities and site. As the federal government unveils its newest plan, this story examines how a lot these houses will value, who really qualifies, and whether or not poor Nigerians can really afford them. BIDON MIBZAR studies.
For hundreds of thousands of Nigerians, the dream of proudly owning a house is slipping additional out of attain as rising rents, hovering constructing prices and shrinking disposable incomes flip homeownership right into a luxurious relatively than a primary aspiration.
Now, the federal authorities’s promise to offer 77,400 social houses nationwide has rekindled hopes of a breakthrough. But with many households struggling to afford meals, transportation, and lease, a troubling query stays: Will these homes be reasonably priced to the poor, or will they develop into one other authorities promise that continues to be past the attain of those that want them most?
The problem goes past developing homes. It is about whether or not a meals vendor, a mechanic, a low-income civil servant, or a petty dealer can safe a house with out exhausting years’ financial savings or committing to repayments that their earnings can not maintain.
For Mercy John, a meals vendor on the Federal Secretariat in Abuja, the uncertainty begins with not figuring out how the mortgage system works or whether or not folks like her can profit with out figuring out somebody influential.
John stated she was unfamiliar with the procedures for contributing to the National Housing Fund (NHF), a government-backed scheme designed to mobilise funds for housing finance. She additionally expressed doubts about whether or not atypical residents might safe mortgage loans with out private connections.
She advised that seeing different atypical Nigerians efficiently receive housing loans might encourage her to discover the scheme herself. Her expertise displays a broader concern that housing initiatives could stay out of attain for potential beneficiaries who don’t perceive the appliance course of or know the place to seek out dependable info.
For Pwausoko James, a federal civil servant primarily based in Maraba, Nasarawa State, the issue isn’t a scarcity of curiosity in proudly owning a house however the problem of saving sufficient cash whereas assembly the every day calls for of household life.
James defined that employees should steadiness lease, meals, transportation, kids’s schooling, healthcare and different important bills earlier than contemplating whether or not they can decide to long-term mortgage repayments.
She welcomed the proposed social housing programme however warned that the variety of homes promised would imply little if buy costs, preliminary deposits and month-to-month repayments remained past the technique of atypical employees.
The federal authorities stated it intends to deal with the housing problem via President Bola Tinubu’s Renewed Hope Social Housing Programme, which targets 100 housing items in every of Nigeria’s 774 native authorities areas, translating to 77,400 houses nationwide.
At the fifteenth National Council on Lands, Housing and Urban Development in Sokoto, held from October 12 to 16, 2026, the Minister of Housing and Urban Development, Dr Muttaqha Rabe Darma, outlined measures meant to enhance housing supply and increase entry to mortgage finance.
The council, themed “Strengthening Mortgage, Land and Institutional Systems for Accelerated and Inclusive Housing Delivery,” introduced collectively authorities officers, housing professionals and different stakeholders to look at reforms in land administration, mortgage finance, institutional regulation and reasonably priced housing provision.
Darma stated the federal government’s strategy was designed to deal with not solely the housing scarcity but in addition the monetary and administrative limitations that stop Nigerians from turning into owners.
However, for James and different low-income employees, the vital difficulty stays whether or not the proposed houses will include fee preparations that replicate their earnings.
Usman Jubril, a automobile mechanic primarily based in Apo, Abuja, stated artisans and different self-employed employees usually wrestle to fulfill the documentation necessities imposed by monetary establishments.
He defined that though some artisans earn sufficient to help their households and meet common bills, their earnings fluctuate, making it troublesome to show the steady revenue historically anticipated of mortgage candidates.
Jubril warned {that a} housing scheme designed primarily round salaried employees might exclude a considerable proportion of Nigerians who depend upon casual employment for his or her livelihoods.
Another concern raised by Awal Yusuf, primarily based in Sokoto, is the necessity to make sure that housing interventions handle the realities of communities past Nigeria’s main city centres.
For residents in numerous elements of the nation, housing affordability is influenced by native land costs, development supplies, infrastructure availability and family buying energy.
Responding to considerations concerning the monetary exclusion of casual employees, Darma stated the federal government was directing the Federal Mortgage Bank of Nigeria (FMBN) to allocate between 30 and 40 per cent of mortgage bookings to the casual sector.
The measure is meant to increase entry to housing finance for Nigerians whose livelihoods depend upon buying and selling, small companies, artisan companies and different types of self-employment.
Darma additionally directed FMBN to disburse not less than 70 per cent of the earlier 12 months’s National Housing Fund contributions yearly via mortgages.
The minister’s place locations mortgage supply on the centre of the federal government’s housing reform agenda, with the goal of guaranteeing that contributions collected from employees translate into extra tangible alternatives for homeownership.
He introduced a goal of delivering 2,000 mortgages in 2026 and growing the determine to five,000 by 2028.
Darma additionally disclosed plans to extend the utmost mortgage mortgage out there via FMBN from N50 million to N85 million by 2028.
The proposed enhance is meant to enhance debtors’ capability to buy houses in a market the place property and development prices have risen significantly.
However, findings by LEADERSHIP Weekend point out {that a} greater borrowing ceiling doesn’t mechanically make homeownership reasonably priced to Nigerians incomes modest incomes. Interest charges, preliminary deposits, compensation intervals, property costs and month-to-month earnings will proceed to find out whether or not potential patrons can maintain their obligations.
For Jubril and different self-employed Nigerians, the sensible take a look at shall be whether or not mortgage establishments introduce versatile compensation schedules, accessible documentation necessities and applicable strategies of assessing irregular incomes.
Without such changes, allocating a proportion of mortgage bookings to informal-sector employees could not mechanically translate into wider entry for mechanics, meals sellers, merchants and different low-income earners.
Also on the Sokoto council, Darma’s reform agenda prolonged past mortgage finance to incorporate measures meant to enhance land administration, regulate the housing market and strengthen protections for homebuyers.
The minister recognized delays in land titling, registration backlogs, opaque procedures and weak land info programs as components that enhance growth prices and discourage funding within the housing sector.
He urged state governments to contribute land for federal housing initiatives and share housing information with the nationwide system.
Darma additionally known as for reforms to speed up land titling, set up digital land registries, deploy geospatial expertise and enhance land administration.
These measures are meant to scale back administrative bottlenecks and make land transactions extra clear, probably serving to to decrease among the prices related to housing growth.
For potential owners, nevertheless, the important thing difficulty is whether or not financial savings from extra environment friendly land administration will translate into decrease home costs.
Where builders face prolonged approval processes, unsure land possession or costly registration procedures, these prices could finally be handed on to purchasers.
For low-income earners, each further cost could make the distinction between qualifying for a house and remaining in rented lodging.
The Sultan of Sokoto, Alhaji Muhammad Sa’advert Abubakar III, additionally known as for stronger collaboration amongst stakeholders to enhance entry to reasonably priced lodging.
His intervention bolstered the significance of cooperation amongst federal and state governments, housing establishments, personal builders and different stakeholders in addressing an issue that extends past the capability of any single establishment.
State governments might want to determine appropriate places, present land the place doable, facilitate approvals and coordinate infrastructure growth if the proposed nationwide housing goal is to be achieved.
The authorities should additionally make clear how the houses shall be financed and constructed, the supply timetable, the function of personal builders, and the mechanisms for monitoring expenditure.
Beyond development and financing, the situation of the housing estates themselves will decide whether or not the programme delivers lasting advantages.
Darma stated the federal government meant to require estates beneath the Renewed Hope Social Housing Programme to fulfill neighborhood integration requirements, together with electrical energy, water, a well being publish, a schoolroom and a tarred entry street.
The proposed necessities recognise that respectable housing entails greater than offering 4 partitions and a roof.
However, for low-income households, the situation of an property and the price of travelling to workplaces, colleges and healthcare amenities may be as essential as the worth of the home.
Darma stated the federal government was creating a National Housing and Built Environment Regulation Policy meant to deal with developer licensing, homebuyer safety, skilled registration, development high quality requirements and housing information.
Under the proposed framework, builders can be licensed, funds collected from homebuyers can be held in escrow, and penalties would apply when builders failed to finish their initiatives.
The minister additionally cited Ghana’s institution of a Real Estate Agency Board for example of how regulation might assist professionalise the sector and enhance client confidence.
The proposed coverage might strengthen protections for folks investing their financial savings in homeownership, notably these taking part in government-backed housing initiatives.
Another main dedication introduced on the Sokoto council, LEADERSHIP Weekend gathered, was the National Housing Data Programme, which can embrace Nigeria’s first National Urban Slum Census.
Darma stated the nation lacked dependable, present and nationally constant housing information, making it troublesome to find out the variety of present housing items, determine quickly increasing slum communities and design interventions for these most in want.
The deliberate programme is predicted to strengthen the data out there to policymakers on housing circumstances and the distribution of demand throughout the nation.
Dr. Aminu Usman, an Economics graduate who completed with a first-class diploma and a employees member of the Central Bank of Nigeria, stated dependable information can be important to figuring out the place demand for social housing was biggest.
He defined {that a} programme protecting all 774 native authorities areas would require correct details about family incomes, housing circumstances, inhabitants distribution and the variety of folks unable to afford respectable lodging.
According to him, dependable information would additionally make it simpler to evaluate whether or not the homes have been reaching the meant beneficiaries.
His place highlights the significance of creating housing information a software for accountability relatively than proscribing its use to authorities planning.
For John, higher public communication can be a essential a part of the method. For James and Jubril, correct information might assist policymakers perceive why formal employees and casual earners encounter completely different limitations to homeownership.
Darma additionally urged state governments to cultivate related housing and concrete planning laws, contribute land to federal initiatives and share information with the nationwide housing system.
He cited Brazil’s Minha Casa Minha Vida programme for example of how cooperation between federal and state authorities might help large-scale housing supply.
The proposed social housing programme will subsequently require coordination throughout completely different ranges of presidency, notably in land administration, planning approvals, infrastructure provision and the identification of native housing wants.
A federal programme can not ship homes successfully in communities the place land is unavailable, approvals are delayed or important infrastructure isn’t offered.
Each state might want to determine appropriate places, set up clear implementation duties and be certain that infrastructure is offered with out undermining affordability.
The fifteenth National Council on Lands, Housing and Urban Development has outlined an bold reform agenda protecting mortgage finance, land administration, institutional regulation, housing information and social housing.
The Federal Government’s proposed 77,400 houses might increase entry to respectable lodging, whereas the deliberate enhance in mortgage supply, the upper mortgage ceiling and the allocation of 30 to 40 per cent of mortgage bookings to informal-sector employees might assist handle longstanding limitations to housing finance.
The council’s discussions additionally highlighted the significance of bettering land registration, strengthening cooperation between federal and state governments, defending homebuyers and creating dependable housing information to information interventions.
Taken collectively, these measures counsel that the federal government’s housing agenda extends past growing the variety of buildings to reforming the programs via which land is acquired, houses are financed, and patrons are protected.
But the experiences of atypical Nigerians present why the programme’s success can’t be measured by targets and coverage bulletins alone.
For John, the instant problem is knowing find out how to take part within the National Housing Fund and whether or not atypical folks can entry loans with out private connections.
For James, the priority is whether or not a daily wage can help the deposit and repayments required to personal a house.
For Jubril, the query is whether or not a mechanic with irregular earnings can qualify for a mortgage designed round typical employment data.
For Awal Yusuf and different residents outdoors main city centres, the problem consists of guaranteeing that housing interventions replicate native circumstances, land availability and buying energy.
For Dr Aminu Usman, dependable information and cooperation between completely different ranges of presidency shall be important to measuring progress.
Their considerations level to the necessity for a housing programme that’s not solely bold in scale but in addition accessible, clear and aware of the realities of atypical households.
The authorities should clarify how beneficiaries shall be chosen, what the homes will value, how funds shall be structured and what safeguards will stop the programme from being captured by candidates who’re higher positioned financially.
It should additionally present clear details about the National Housing Fund, increase public consciousness, publish implementation timelines and show how the promised homes shall be delivered throughout the nation.
The deliberate allocation of mortgage bookings to informal-sector employees should translate into accessible monetary merchandise, whereas the proposed land and regulatory reforms should produce tangible reductions within the limitations confronting potential owners.
Ultimately, Nigerians will choose the Sokoto council not by the variety of speeches delivered or resolutions adopted, however by whether or not households who’ve struggled for years to safe respectable lodging can lastly afford a house of their very own.
The federal authorities has set an bold goal of 77,400 social houses and outlined reforms meant to increase entry to housing finance, enhance land administration and strengthen client safety.
The vital query stays: Will these commitments make homeownership doable for poor Nigerians, or will the price of buying a home proceed to position the dream past their attain?
We’ve received the sting. Get real-time studies, breaking scoops, and unique angles delivered straight to your telephone. Don’t accept stale information. Join LEADERSHIP NEWS on WhatsApp for twenty-four/7 updates →