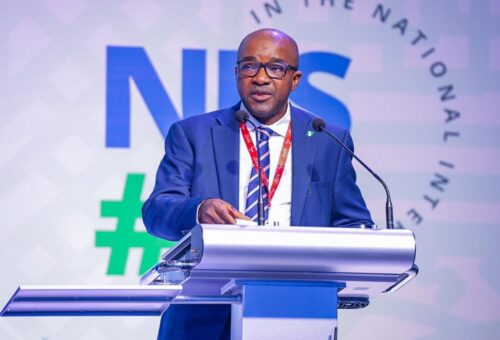
The Minister of Finance and Coordinating Minister of the Economy, Taiwo Oyedele, has cautioned governments towards introducing new taxes or growing present tax burdens on susceptible residents and productive sectors, warning that such measures might deepen financial hardship.
Oyedele spoke on Tuesday on the sidelines of the 2026 annual conferences of the International Monetary Fund (IMF) and World Bank in Bangkok, Thailand, the place he learn a communiqué on behalf of the Intergovernmental Group of Twenty-Four (G24), which he serves as Chairman.
“This is the wrong time to impose new taxes or increase the burden of tax, particularly on the vulnerable population and productive sectors of the economy,” he stated.
Responding to questions on how creating nations might cut back debt-servicing prices with out slicing important public spending, Oyedele urged governments to establish waste, discover financial savings and enhance income assortment earlier than inserting extra monetary stress on residents and companies.
He stated borrowing remained vital to finance financial progress however pressured that governments should make sure that debt helps job creation and inclusive improvement.
“Borrowing and debt financing is a necessary condition for growth, and every country emerging, developing must be able to apply debt financing in a way that is overall of positive impact, particularly to stimulate job-rich and inclusive growth,” he stated.
The minister additionally known as for out there public funds to be prioritised for important companies, together with healthcare and training, whereas non-public capital might assist finance different areas of funding.
On the selection between taxation and borrowing, Oyedele stated each choices carried penalties and needs to be thought of within the context of their affect on family welfare.
“If you collect taxes, you raise the money now, and that itself has a lot of trade-offs. What taxes are you collecting? You collect taxes from the most vulnerable, and this will deprive them of money to provide food, health, education,” he stated.
He argued that extreme taxation might depart low-income households with much less cash for primary wants, whereas borrowing additionally carried future obligations.
“Debt is future taxes, so it’s not one or the other. It’s to strike a balance, bearing in mind ultimately that the essence of tax and of debts is to cater for the people,” Oyedele stated.
…IMF warns of rising poverty, meals insecurity
Meanwhile, the International Monetary Fund (IMF) has upgraded its forecast for Nigeria’s financial progress in 2026 to 4.2 % from 4.1 %, whereas warning that greater meals and vitality costs might worsen poverty and meals insecurity.
The Washington-based establishment introduced the revision in its October 2026 World Economic Outlook (WEO) report launched on Tuesday.
The IMF stated Nigeria’s financial system is benefiting from improved macroeconomic stability and beneficial terms-of-trade results, however warned that rising costs of important items would put additional stress on households.
“Higher prices for essentials are expected to further aggravate poverty and food insecurity,” the fund stated.
At a press briefing on the report, Deniz Igan, chief of the IMF analysis division’s world financial research division, stated the federal government wants to stability quick assist for households with the necessity to preserve fiscal stability over the medium time period.
“What we are advocating for is for policymakers to balance the near-term needs of the population, and that involves food security, that involves energy security,” Igan stated.
She stated the price of meals and vitality is rising disproportionately in Nigeria, making it more durable for susceptible households to address the price of residing.
Using Nigeria for instance, Igan stated financial progress had held up partly as a result of the nation exports vitality, however poverty dangers stay excessive.
“While the growth held up in Nigeria, given energy exporter, poverty risks are still very high,” she stated.
“What we’re advocating for is cash transfers, income support, targeted temporary income support for the most vulnerable households in Nigeria.”
The IMF analysis chief stated such interventions needs to be in keeping with the federal government’s medium-term fiscal framework.
The IMF expects financial progress in sub-Saharan Africa to stay at 4.5 % in 2026, though it stated the regional forecast masks important variations amongst nations.
The report stated progress prospects depend upon nations’ fiscal capability, progress with reforms, publicity to commodity costs, local weather shocks and entry to exterior financing.
UPDATE NEWS:
Nigerians can now make investments ₦2.5 million on premium domains and revenue about ₦17-₦25 million. All earnings paid in US Dollars. Rather than surprise,
click here to find out how it works.