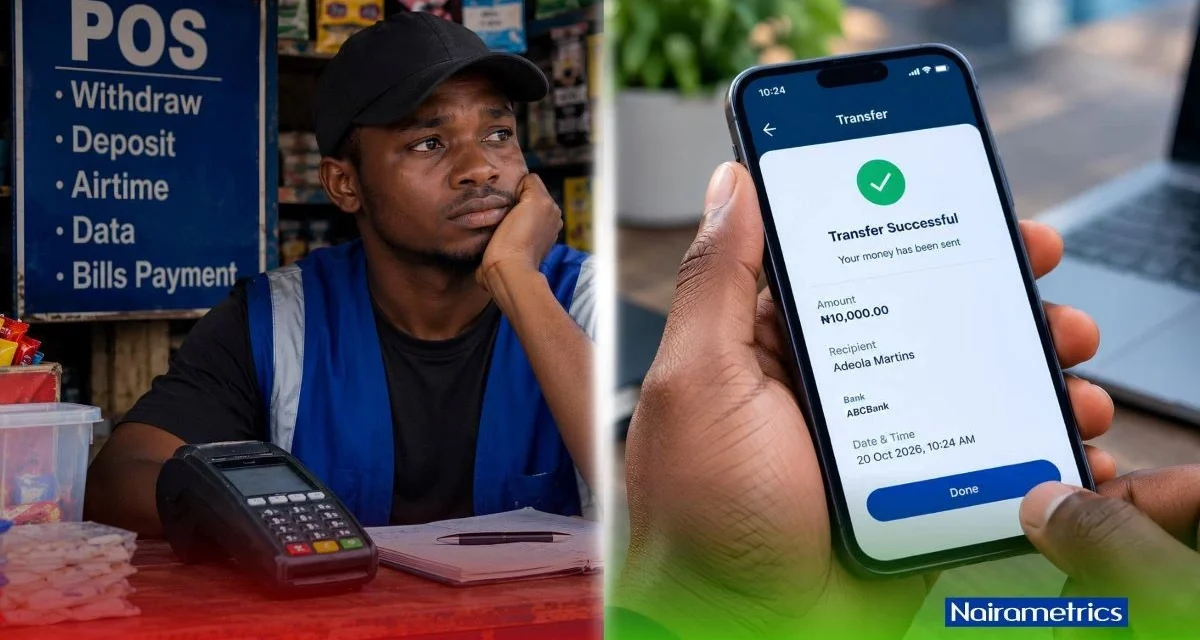

Nigeria’s huge Point-of-Sale (PoS) company banking community is going through rising stress as customers more and more abandon money withdrawals in favour of direct mobile transfers, elevating issues concerning the long-term sustainability of hundreds of PoS companies throughout the nation.
The pattern is strengthened by findings from the GSMA’s State of the Industry Report on Mobile Money 2026, which confirmed that mobile cash adoption continues to speed up worldwide.
According to the report, the variety of registered mobile cash accounts globally reached 2.3 billion in 2025, whereas lively 30-day accounts rose to 593 million, pushing the worldwide month-to-month exercise fee to 25.7%.
The report additionally revealed that greater than $2.1 trillion flowed by mobile cash platforms in 2025, with transaction values rising sooner than transaction volumes.
Shift in shopper behaviour
For years, PoS operators crammed a important hole in Nigeria’s monetary ecosystem, offering easy accessibility to money at a time when ATM queues, money shortages, and banking service disruptions have been frequent.
However, the fast adoption of mobile banking purposes, fintech platforms, and digital wallets is reshaping shopper behaviour, with extra Nigerians now selecting to switch cash on to retailers, merchants, transport operators, and repair suppliers moderately than withdrawing money.
The shift displays the broader transition towards a cashless financial system, the place transactions more and more stay inside the digital ecosystem.
Nigerians who spoke with Nairametrics mentioned they’re extra snug making mobile transfers for nearly each transaction, besides on only a few events after they want money.
Gradual decline in money transaction
Several PoS agents famous that altering shopper habits are proving much more difficult.
- “Customers are not really collecting cash again like before. Now a lot of people are doing transfer; even ‘aboki’ that are selling yam and tomatoes are collecting transfers. So many PoS agents are shutting down,” Evelyn Owoh mentioned.
The rising acceptance of mobile transfers amongst small companies and casual merchants has considerably decreased the necessity for money withdrawals, historically the spine of the PoS enterprise mannequin.
Another PoS operator say the decline in money transactions may very well be as a results of stricter rules and rising competitors inside the sector.
Speaking with Nairametrics, the Lagos-based PoS agent, Bukola, mentioned current regulatory measures have affected the enterprise.
- “Strict Central Bank of Nigeria (CBN) rules, including single-principal exclusivity limits, and daily volume caps, have affected the business.”
Operators say many places that after supported a handful of agents now have dozens of competing companies serving the identical buyer base.
Fintechs driving monetary inclusion
CEO and Co-Founder of Sycamore, Babatunde Akin-Moses, informed Nairametrics that Nigeria’s fast shift towards digital financial institution transfers is pushed by a mix of necessity, fintech accessibility, price effectivity, and community results.
He recalled that the 2023 money shortage initially pressured residents to embrace transfers, reworking an emergency workaround right into a long-term shopper behavior. Concurrently, fintech platforms made opening and working accounts considerably simpler for casual merchants and unusual residents, whereas digital transfers supplied a less expensive, extra handy various to paying POS withdrawal fees.
According to him, as shopper choice for transfers mounted, a self-reinforcing community impact compelled retailers to adapt, steadily lowering the necessity to carry bodily foreign money.
- “This evolution is rebalancing traditional payment channels, presenting both challenges and strategic opportunities across the financial landscape. POS agents reliant strictly on cash withdrawals face declining patronage in urban centers, though those diversifying into broader financial services can remain relevant.”
- “I also wouldn’t conclude that POS and ATMs are disappearing. According to the CBN’s Q1 2026 figures, mobile payment volumes grew by about 29% year-on-year, while POS transaction volumes declined by approximately 20%. Interestingly, ATM transaction volumes still increased by about 7%,” he mentioned.
He mentioned Nigeria is transitioning into an period the place money capabilities as a specialised utility moderately than the default medium for routine funds.
- “My opinion is that we’re moving towards an economy where people withdraw cash because they actually need cash, rather than because they need cash to make a payment.”
A fintech skilled who doesn’t need his title talked about due to the organisation he works for mentioned the transition from bodily money channels to mobile transfers mirrors the historic evolution of Nigeria’s telecommunications sector.
Just as customers shifted from shopping for paper recharge playing cards from roadside distributors to seamless digital top-ups, he mentioned monetary funds are present process a pure channel evolution.
He mentioned on the core of this transformation is person comfort and mutual acceptability, noting that digital transfers get rid of transaction dangers, guide enter errors, and POS withdrawal surcharges, making direct transfers the more and more most well-liked alternative.
He, nevertheless, famous that regardless of the rise in mobile transfers, POS agents are unlikely to endure a major adverse influence as a consequence of ongoing money dependency.
- “Nigeria remains a heavily cash-driven economy for daily micro-transactions, such as public transportation where digital transfers are impractical. Furthermore, while mobile transfer adoption is concentrated in urban trade centres, POS terminals and ATMs serve as indispensable last-mile cash sources in underserved communities where digital coverage is less pervasive.”
He mentioned moderately than changing into out of date, POS networks are evolving into low-cost distribution hubs for broader monetary merchandise, including that as a result of POS {hardware} is much cheaper to deploy and preserve than conventional ATMs, monetary establishments are actively layering new providers onto these last-mile rails—starting from capital market operations just like the Dangote IPO gross sales through agent networks to future choices in insurance coverage, pensions, and investments.
What you must know
According to Nairametrics’ analysis of the Central Bank of Nigeria’s (CBN) Balance of Payments Highlights for the first and second quarters of 2026, Nigeria acquired $11.12 billion in private transfers.
It elevated from $5.30 billion within the first quarter to $5.82 billion within the second quarter, representing a quarterly rise of $520 million, or 9.8%.
Personal transfers rose to $5.82 billion in Q2 2026 from $5.30 billion in Q1, bringing whole inflows for the primary six months of the yr to $11.12 billion.